📋 Table of Contents
- 1. Statutory Legal Framework: Tenth Schedule & The Double Taxation Rule
- 2. Visual Infographic: Filer vs Non-Filer Withholding Tax Matrix
- 3. Bank Cash Withdrawal & ATM Tax Rules (Section 231AB / 236Y)
- 4. Complete Filer vs Non-Filer Rates Comparison Table (8 Major Transactions)
- 5. Property Purchase & Sale Tax Rates: Section 236K & 236C Multipliers
- 6. Motor Vehicle Registration, Token Tax & Transfer Penalties (Section 231B)
- 7. Bank Profits, Stock Dividends & Prize Bonds (Section 150 & 151)
- 8. Real-Life Financial Case Study: The Rs. 450,000 Non-Filer Loss
- 9. Step-by-Step Legal Procedure to Convert from Non-Filer to Active Filer
- 10. Frequently Asked Questions (FAQs)
In Pakistan's current fiscal landscape governed by the Income Tax Ordinance 2001 and the updated Finance Act 2025–2026, holding legal "Active Filer" status on the Federal Board of Revenue (FBR) Active Taxpayer List (ATL) is no longer optional—it is a critical financial shield. The government has systematically enforced punitive withholding tax rates on non-filers and inactive citizens, imposing 100% to 300% tax surcharges on daily banking transactions, ATM withdrawals, vehicle purchases, and property registrations. This authoritative guide breaks down every statutory tax rate comparison so you can protect your hard-earned wealth.
1. Statutory Legal Framework: Tenth Schedule & The Double Taxation Rule
Under Section 181A and the Tenth Schedule to the Income Tax Ordinance 2001, the Federal Board of Revenue operates a bifurcated tax structure designed to document the formal economy. The law establishes two distinct categories of individual and corporate taxpayers:
✅ Active Taxpayer (Filer)
An individual, AOP, or company whose name appears on the published Active Taxpayer List (ATL). Filers pay standard baseline withholding taxes, are completely exempt from banking cash withdrawal levies, and can adjust advance taxes against their final annual tax liabilities.
⚠️ Inactive / Non-Filer
Any citizen whose CNIC is missing from the active list due to non-submission of annual tax returns or non-payment of Section 182A surcharges. Non-filers are subjected to automatic double withholding tax (2x to 4x baseline rates) across all commercial activities.
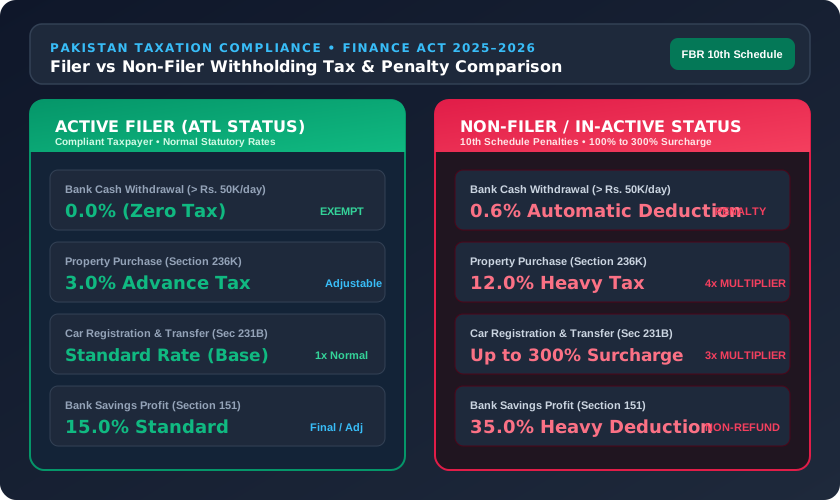
2. Visual Infographic: Filer vs Non-Filer Withholding Tax Matrix
The reference matrix below highlights the massive disparity in withholding tax deductions applied across everyday commercial banking, property, and vehicle transactions:
3. Bank Cash Withdrawal & ATM Tax Rules (Section 231AB / 236Y)
One of the most frequently asked tax questions in Pakistan pertains to banking deductions: "Is tax deducted when I withdraw my own cash from the bank?"
Under Section 231AB of the Income Tax Ordinance 2001, the rules for cash withdrawals are strictly divided by filer status:
- For Active Filers: 0.00% (Completely Exempt). Filers can withdraw any cash amount (e.g. Rs. 5 Lakh, Rs. 10 Lakh, or Rs. 50 Lakh) across bank counters, online transfers, or ATMs without paying a single rupee in cash withdrawal tax.
- For Non-Filers (The Rs. 50,000 Daily Threshold Rule): Every banking institution in Pakistan is legally mandated to deduct advance withholding tax at 0.6% on the entire aggregate cash withdrawal if the total cash withdrawn in a single calendar day exceeds PKR 50,000 across all branches of that bank.
-
How the 0.6% Threshold Math Works:
- If a non-filer withdraws PKR 45,000 in a day: Tax deducted = PKR 0 (below threshold).
- If a non-filer withdraws PKR 50,000 in a day: Tax deducted = PKR 0.
- If a non-filer withdraws PKR 51,000 in a day: 0.6% applies to the entire amount = PKR 306 automatically deducted.
- If a non-filer withdraws PKR 500,000 for business payroll: 0.6% = PKR 3,000 deducted instantly!
4. Complete Filer vs Non-Filer Rates Comparison Table (8 Major Transactions)
The table below summarizes the statutory withholding tax rates applicable to Filers vs Non-Filers under the Finance Act 2025–2026:
| Transaction Category | Income Tax Section | Active Filer Rate | Non-Filer Rate | Penalty Impact |
|---|---|---|---|---|
| Bank Cash Withdrawal (> Rs. 50K/day) | Section 231AB | 0.00% (Exempt) | 0.60% of total | Automatic deduction |
| Purchase of Immovable Property | Section 236K | 3.00% | 12.00% – 15.00% | 4x to 5x Massive Penalty |
| Sale of Immovable Property | Section 236C | 3.00% | 10.00% | 3.3x Higher Tax |
| Car Registration & Transfer | Section 231B | Standard Base Rate | 200% to 300% Surcharge | 3x Multiplier |
| Bank Savings & Profit on Debt | Section 151 | 15.00% | 35.00% | More than double |
| Stock Market Dividends | Section 150 | 15.00% | 30.00% | Double Deduction |
| National Prize Bond Winnings | Section 156 | 15.00% | 30.00% | Double Deduction |
| International Card Transactions | Section 236Y | 5.00% | 10.00% | 100% Surcharge |
5. Property Purchase & Sale Tax Rates: Section 236K & 236C Multipliers
Real estate is where non-filers suffer the most devastating financial penalties. Under FBR regulations, provincial land revenue authorities (Sub-Registrars), housing societies (such as DHA, Bahria Town, CDA, LDA), and cooperative housing bodies cannot register property transfers without verifying CPR challans under Section 236K and 236C:
-
Section 236K (Buyer Advance Tax): When purchasing a plot, commercial building, or residential house:
- Filer: Pays a standard 3% advance tax on the FBR valuation or DC rate. This entire 3% is adjustable against annual income tax!
- Non-Filer: Pays a punitive 12% to 15% withholding tax. On a PKR 1 Crore plot, a filer pays PKR 300,000 while a non-filer pays PKR 1,200,000—a direct loss of PKR 900,000!
-
Section 236C (Seller Advance Tax): When selling property:
- Filer: Pays 3% advance withholding tax.
- Non-Filer: Pays 10% advance withholding tax.
6. Motor Vehicle Registration, Token Tax & Transfer Penalties (Section 231B)
Excise and Taxation Departments in Punjab, Sindh, Khyber Pakhtunkhwa, and Islamabad impose heavy non-filer surcharges at the time of purchasing new assembled cars or transferring used registered vehicles:
- Small Vehicles (Up to 850cc - e.g. Suzuki Alto): Filers pay PKR 10,000 advance tax, whereas non-filers pay PKR 30,000 (300% penalty).
- Compact Sedans (1000cc to 1300cc - e.g. Toyota Yaris, Honda City): Filers pay PKR 25,000, whereas non-filers pay PKR 75,000.
- Mid-Size Vehicles (1301cc to 1800cc - e.g. Corolla, Civic, Elantra): Filers pay PKR 75,000, whereas non-filers pay PKR 225,000.
- SUVs & Luxury Vehicles (Exceeding 2000cc - e.g. Fortuner, Prado): Non-filers pay massive surcharges exceeding PKR 600,000 to PKR 1,000,000+ at the showroom.
7. Bank Profits, Stock Dividends & Prize Bonds (Section 150 & 151)
Passive investments and savings deposits are taxed automatically at source via commercial bank software:
- Profit on Debt (Section 151): If your bank account earns PKR 100,000 annual profit from a savings account or term deposit certificate, a filer receives PKR 85,000 after 15% tax. A non-filer receives only PKR 65,000 after an exorbitant 35% deduction.
- PSX Stock Dividends (Section 150): Filers pay 15% dividend tax; non-filers pay 30%.
- Prize Bond Winnings (Section 156): Winning a PKR 1,500,000 prize bond yields PKR 1,275,000 for a filer (15% tax) but only PKR 1,050,000 for a non-filer (30% tax—an immediate loss of PKR 225,000).
8. Real-Life Financial Case Study: The Rs. 450,000 Non-Filer Loss
Consider Mr. Tariq, an Islamabad businessman who delayed filing his annual tax return because he considered it "cumbersome". In August 2025, Mr. Tariq conducted two routine commercial transactions:
Case Study Scenario:
- Transaction 1: Purchased a 1300cc new family car (Invoice: PKR 4.5 Million).
- Transaction 2: Purchased a 5-Marla residential plot in Lahore (DC value: PKR 3.5 Million).
Tax Cost Breakdown Comparison:
-
Car Registration Advance Tax (Section 231B):
If Active Filer: PKR 25,000.
As Inactive Non-Filer: PKR 75,000 (Loss: PKR 50,000). -
Property Purchase Advance Tax (Section 236K):
If Active Filer (3% of 3.5M): PKR 105,000.
As Inactive Non-Filer (12% of 3.5M): PKR 420,000 (Loss: PKR 315,000). -
Bank Cash Withdrawal for Seller Token Money (PKR 500,000):
If Active Filer (0%): PKR 0.
As Inactive Non-Filer (0.6%): PKR 3,000. -
Total Money Lost by Being Non-Filer:
PKR 50,000 + PKR 315,000 + PKR 3,000 = PKR 368,000 Extra Tax Paid!
By spending just a few thousand rupees to file his tax return, Mr. Tariq could have saved over PKR 368,000 in cash on these two transactions alone!
9. Step-by-Step Legal Procedure to Convert from Non-Filer to Active Filer
Regaining active filer status on FBR Iris is a clear, standardized procedure:
-
1
Obtain FBR Iris Access Credentials:
If you do not have an NTN, register online at iris.fbr.gov.pk using your CNIC and biometric mobile number.
-
2
Draft and Submit Your Income Tax Return:
Submit your annual declaration of income (Salary, Business, Rent, or Foreign Remittance) along with your statutory Wealth Statement (assets and liabilities).
-
3
Generate Section 182A Surcharge CPR:
If filing after the statutory deadline, generate an e-challan under Section 182A (PKR 1,000 for individual salaried/business persons) and deposit it via NBP, 1Link ATM, or JazzCash/Easypaisa.
-
4
Instant Verification on 9966 SMS:
Verify your live activation status by texting
ATL <space> 13-digit CNICto 9966. Your status will reflect as "Active" immediately across all commercial banks.