📋 Table of Contents
- 1. Why the Rs. 50,000 to Rs. 100,000 Salary Bracket is Crucial
- 2. Visual Progression: Monthly Tax on Rs. 50K to 1 Lakh Salaries
- 3. The Mechanics of FBR Slab 2: The 5% Progressive Rate
- 4. Granular Salary-by-Salary Calculation Schedule (50K to 100K)
- 5. Real-Life Case Study: Payroll Slip for Rs. 85,000 Monthly Salary
- 6. What Happens When a Raise Pushes You Beyond Rs. 100,000?
- 7. How to Completely Offset Your Tax with Mobile & Electricity WHT
- 8. Guidance for HR & Payroll Teams Managing Section 149 Deductions
- 9. Frequently Asked Questions (FAQs)
The monthly salary range between PKR 50,000 and PKR 100,000 (1 Lakh) represents the vast majority of Pakistan's entry-level, junior executive, and middle-class workforce. Under the updated Finance Act 2025–2026, crossing the PKR 50,000 monthly threshold transitions an employee from the tax-free zone into FBR Salary Tax Slab 2. This guide provides exact, rupee-by-rupee calculations, monthly deductions, annual tax amounts, and take-home pay breakdowns across this pivotal income bracket.
1. Why the Rs. 50,000 to Rs. 100,000 Salary Bracket is Crucial
In Pakistan's corporate landscape—ranging from software houses and banks to retail operations and schools—this salary band captures young professionals, assistant managers, accountants, and officers.
Many workers entering this bracket mistakenly fear that entering the tax net will consume a huge portion of their paycheck. The reality, however, is much more moderate:
2. Visual Progression: Monthly Tax on Rs. 50K to 1 Lakh Salaries
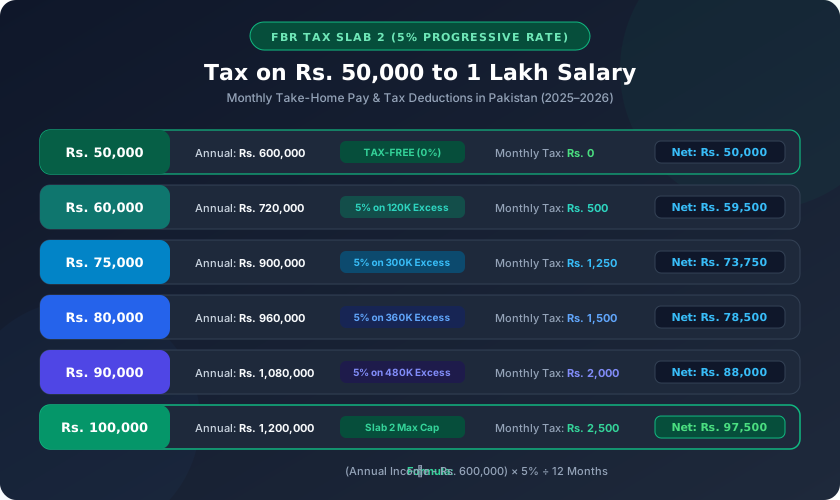
The reference diagram below highlights how tax deductions and net take-home salaries progress as monthly earnings rise from PKR 50,000 to PKR 100,000:
3. The Mechanics of FBR Slab 2: The 5% Progressive Rate
Under Division I, Part I of the First Schedule to the Income Tax Ordinance 2001, annual income between PKR 600,001 and PKR 1,200,000 is taxed under Slab 2:
- Fixed Base Tax: PKR 0
- Marginal Tax Rate: 5% on the portion of income that exceeds PKR 600,000.
- The Mathematical Formula:
Annual Tax = (Annual Taxable Salary - 600,000) × 0.05Monthly Tax = Annual Tax ÷ 12
4. Granular Salary-by-Salary Calculation Schedule (50K to 100K)
Here is the comprehensive breakdown for every PKR 5,000 to PKR 10,000 step within this bracket. This data provides the exact legal payroll deductions:
| Monthly Salary | Annual Income | Excess over 600K | Monthly Tax | Annual Tax | Net Take-Home | Effective Rate |
|---|---|---|---|---|---|---|
| Rs. 50,000 | Rs. 600,000 | Rs. 0 | Rs. 0 | Rs. 0 | Rs. 50,000 | 0.00% |
| Rs. 55,000 | Rs. 660,000 | Rs. 60,000 | Rs. 250 | Rs. 3,000 | Rs. 54,750 | 0.45% |
| Rs. 60,000 | Rs. 720,000 | Rs. 120,000 | Rs. 500 | Rs. 6,000 | Rs. 59,500 | 0.83% |
| Rs. 65,000 | Rs. 780,000 | Rs. 180,000 | Rs. 750 | Rs. 9,000 | Rs. 64,250 | 1.15% |
| Rs. 70,000 | Rs. 840,000 | Rs. 240,000 | Rs. 1,000 | Rs. 12,000 | Rs. 69,000 | 1.43% |
| Rs. 75,000 | Rs. 900,000 | Rs. 300,000 | Rs. 1,250 | Rs. 15,000 | Rs. 73,750 | 1.67% |
| Rs. 80,000 | Rs. 960,000 | Rs. 360,000 | Rs. 1,500 | Rs. 18,000 | Rs. 78,500 | 1.88% |
| Rs. 85,000 | Rs. 1,020,000 | Rs. 420,000 | Rs. 1,750 | Rs. 21,000 | Rs. 83,250 | 2.06% |
| Rs. 90,000 | Rs. 1,080,000 | Rs. 480,000 | Rs. 2,000 | Rs. 24,000 | Rs. 88,000 | 2.22% |
| Rs. 95,000 | Rs. 1,140,000 | Rs. 540,000 | Rs. 2,250 | Rs. 27,000 | Rs. 92,750 | 2.37% |
| Rs. 100,000 | Rs. 1,200,000 | Rs. 600,000 | Rs. 2,500 | Rs. 30,000 | Rs. 97,500 | 2.50% |
5. Real-Life Case Study: Payroll Slip for Rs. 85,000 Monthly Salary
Let us trace the exact payroll computation for a customer support supervisor earning a gross monthly package of PKR 85,000 in Karachi:
Compensation Structure:
- Basic Salary: PKR 55,000
- House Rent Allowance (HRA): PKR 24,500
- Medical Allowance (10% of Basic): PKR 5,500
- Gross Monthly Salary: PKR 85,000
Step-by-Step Payroll Tax Calculation:
- Exempt Medical Allowance: Under Clause 139, 10% of Basic (PKR 5,500) is 100% exempt.
- Monthly Taxable Salary: PKR 85,000 - PKR 5,500 = PKR 79,500.
- Annualized Taxable Income: PKR 79,500 × 12 = PKR 954,000.
- FBR Tax Slab: Slab 2 (PKR 600,001 to PKR 1,200,000).
- Excess over 600K: PKR 954,000 - PKR 600,000 = PKR 354,000.
- Annual Tax: 5% of PKR 354,000 = PKR 17,700 per year.
- Monthly Payroll Deduction: PKR 17,700 ÷ 12 = PKR 1,475 per month.
- Net Bank Transfer: PKR 85,000 - PKR 1,475 = PKR 83,525 (Effective tax rate: 1.74%).
6. What Happens When a Raise Pushes You Beyond Rs. 100,000?
A frequent question from employees is: "If my salary increases from Rs. 95,000 to Rs. 105,000, will I end up taking home less money because I crossed into Slab 3?"
The Answer is an Emphatic NO! Pakistan's tax system never causes you to take home less money after a salary raise. Here is why:
- Slab 3 (15% rate) applies ONLY to the incremental income exceeding PKR 1,200,000 (PKR 100,000/month).
- If your salary increases by PKR 10,000 (from 95K to 105K), only the PKR 5,000 that sits above PKR 100,000 is taxed at 15% (PKR 750). The remaining PKR 5,000 is taxed at 5% (PKR 250).
- Total new tax increase: PKR 1,000. Your net take-home salary still increases by PKR 9,000!
7. How to Completely Offset Your Tax with Mobile & Electricity WHT
Here is the best insider secret for salaried individuals in the Rs. 50K to 100K bracket: You can often wipe out your entire annual tax bill or receive an official FBR tax refund!
Consider an employee with an annual tax liability of PKR 15,000 (Rs. 75,000 monthly salary):
- Mobile Phone WHT (Sec 236): Spends PKR 2,500/month on mobile cards and data packages for themselves and family. 15% advance tax = PKR 375/month = PKR 4,500 per year.
- Domestic Electricity WHT (Sec 235): Advance tax on domestic power bills in summer = PKR 6,000 per year.
- Bike / Car Token Tax WHT (Sec 234): Annual motor vehicle token tax deduction = PKR 3,500.
- Internet Broadband WHT: Fiber internet connection advance tax = PKR 1,800 per year.
Result on FBR Iris Return: Your advance deductions exceed your total tax liability of PKR 15,000! You pay ZERO additional tax and have an official PKR 800 refund balance with FBR.
8. Guidance for HR & Payroll Teams Managing Section 149 Deductions
For corporate payroll managers administering deductions under Section 149:
- Ensure that employees submitting medical bills or telecom tax deduction certificates provide verifiable documentation before adjusting payroll withholding.
- Always calculate the annualized average monthly rate rather than applying lump-sum deductions in the final quarter of the fiscal year.
- Issue Section 164 Tax Certificates promptly after June 30 so staff can file their annual Iris returns on time.